Disability Insurance Claims
We offer a free case review to anyone whose disability insurance claim has been denied, delayed, or cut off. We help clients across Louisiana and Texas, including New Orleans, Baton Rouge, Lafayette, Houston, Dallas, and San Antonio, and can represent clients nationwide, working with local counsel where needed. We read the policy, the claim file, and the insurer’s reasons, and we give you a straightforward answer about where your claim stands. If the insurer is wrong, we have the resources and trial experience to aggressively pursue what the policy promised to you.
Protecting Your Income and Your Rights
Disability Insurance Lawyers for Professionals and Working Families
Disability insurance is supposed to replace your income when illness or injury keeps you from working. Insurers collect premiums for years, then look for reasons not to pay once a claim arrives. They often misread medical records, unfairly redefine your work duties to deny coverage, point to an insurer-hired physician who only examined you or reviewed your medical records once, or try to narrowly interpret the policy in ways that are contrary to existing law.
We represent people with disability insurance claims under both kinds of disability coverage:
Employer-sponsored group policies, which are usually governed by the federal law known as ERISA.
Individual policies you bought on your own, which are usually governed by the insurance law of the state where the policy was issued.
The rules for group disability policies and individual disability policies are very different. Knowing which rules apply to your policy is the first thing we determine.
Physician & Medical Professional Disability Claims
Physicians, surgeons, dentists, anesthesiologists, and other medical professionals often carry the most valuable disability coverage, and face the most aggressive claim reviews.
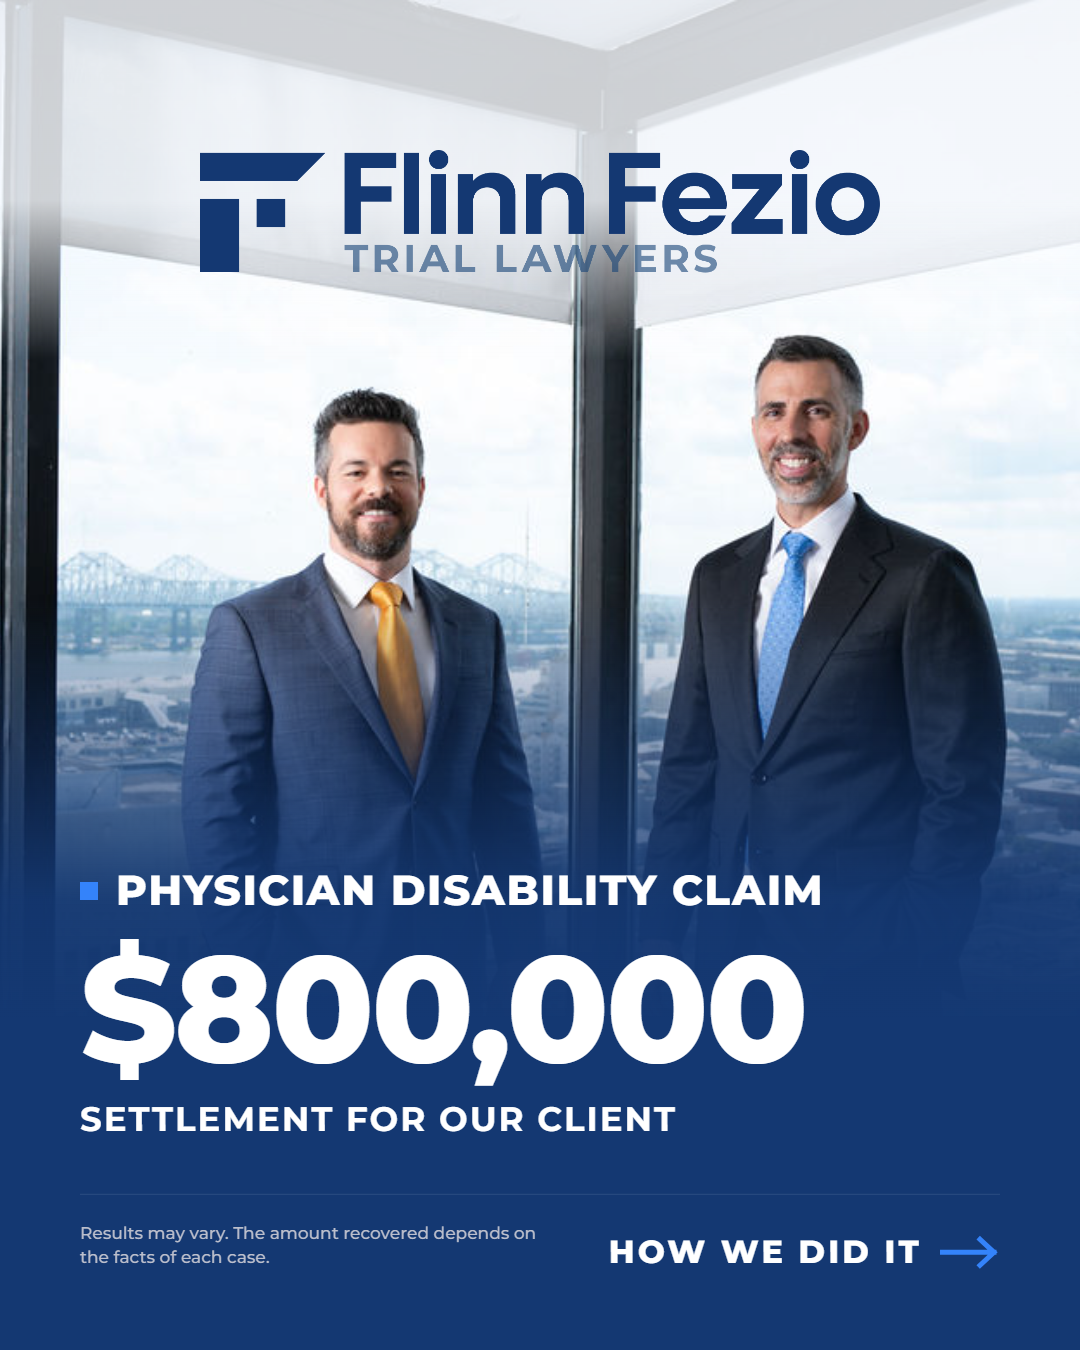
$800,000 Recovered for a Physician
In our most recent disability case, we recovered $800,000.00 for a physician whose insurer denied his disability coverage.
Building Your Claim Step by Step
How We Handle Your Disability Claim
At Flinn Fezio, we actively build your case with evidence to support your claim for disability benefits. By analyzing all your claim documents in detail and identifying weaknesses in the insurer’s claim review process, we can determine how to supplement your claim with strong evidence of your disability. This helps us challenge denials and pursue benefits owed under the policy. You can count on the internal processes we have honed for handling disability insurance claims in New Orleans:
1. Review. We read your denial letter, policy, and plan documents, identify which law applies, and calendar every deadline.
2. Investigate. We look for adjuster errors and misinterpretations of the policy.
3. Build the record. We work with your treating doctors and, where needed, we retain independent specialists and vocational experts to make your case as strong as possible.
4. Present. Depending on the stage of your claim, we can submit an appeal or a formal demand directly to the insurer as needed.
5. Litigate if needed. If the insurer won’t pay, we have the ability to file suit and seek a judgment from the appropriate court.
$800,000 Recovered for a Physician
In our most recent disability case, we recovered $800,000.00 for a physician whose insurer denied his disability coverage.
Nationwide Representation From New Orleans

We Can Represent Clients Nationwide
Most disability coverage provided through an employer is governed by ERISA, a federal law. The same rules, deadlines, and appeal procedures apply whether you live in New Orleans, Houston, Chicago, or anywhere else in the country. That is why we can represent clients nationwide from our New Orleans office.
Appeals happen in writing. The appeal to the insurer is built from records and evidence, so where you live doesn’t limit what we can do.
Meetings fit your schedule. We meet by phone or video, and documents are signed electronically.
Lawsuits go to federal court. If the insurer won’t pay, ERISA cases are filed in federal court.
Individual policies follow state law. Policies you bought yourself are governed by the law of the state where they were issued.
- If the claim needs to be brought in state court outside of Louisiana or Texas we can enroll local counsel in your home state to help bring our disability law knowledge to bear in your local venue if needed.
Types of Disability Claims We Handle
Long-Term Disability & ERISA Claims
Most employer-provided long-term disability claims are governed by ERISA. Your disability insurance appeal is often the last opportunity to put evidence in the record a court will review, so it should be built like a trial file.
Individual Disability Insurance Policies
Individual disability insurance policies are generally governed by the contract and state insurance law. These cases can be tried in court, and many states, including Louisiana, provide penalties in certain circumstances when insurers fail to pay valid claims on time.
Denied or Terminated Claims
Whether you are dealing with denied disability claims or terminated disability benefits, strict deadlines may apply. Reviewing your denial letter and policy promptly helps identify the next steps and the time limits for taking action.
Short-Term Disability
A short-term disability denial may affect the evidence available for a later long-term disability claim. Getting the record right early helps support both, although each claim must meet its own policy requirements.
Which Law Governs Your Disability Claim, and Why It Matters
The law that controls a disability insurance claim depends largely on how the policy was obtained. That distinction can significantly affect both how the claim is decided and which benefits and legal remedies a policyholder may pursue.
Employer-provided policies (ERISA)
Most employer-provided disability policies are governed by the Employee Retirement Income Security Act of 1974 (ERISA), a federal statute. ERISA broadly preempts state laws that relate to employee benefit plans (29 U.S.C. § 1144), subject to exceptions. Benefit disputes under these policies generally follow ERISA’s rules, although some state insurance regulations may still apply.
ERISA has specific legal remedies. A claimant suing under 29 U.S.C. § 1132(a)(1)(B) can generally recover benefits owed under the plan, plus interest and possibly reinstatement of future benefits. Punitive damages and state-law bad-faith damages are generally unavailable for these benefit claims (Pilot Life Ins. Co. v. Dedeaux, 481 U.S. 41, 54–55 (1987)). Attorney fees are available at the court’s discretion (29 U.S.C. § 1132(g)(1)). There is generally no jury trial in an ERISA benefits action. Courts often review the insurer’s decision under a deferential standard when the plan validly grants discretionary authority; otherwise, review is generally de novo (Firestone Tire & Rubber Co. v. Bruch, 489 U.S. 101, 115 (1989)).
Individually purchased policies (state law)
Individual disability policies bought outside an employer-sponsored plan are generally not subject to ERISA. These claims are usually governed by state contract and insurance law. Governmental and most church plans are also exempt from ERISA, but the rules governing those plans require a separate review.
State law may provide additional remedies for wrongful disability insurance denials. Depending on the state and the facts, a claimant may be able to pursue:
- Bad faith claims when an insurer unreasonably denies or delays payment
- Statutory penalties and interest for late or wrongful nonpayment
- Attorney fees, which some state statutes shift to the insurer
- Punitive damages where the insurer's conduct is especially egregious
- Compensatory damages beyond the policy benefits, such as emotional distress or consequential financial losses
- A jury trial is often available to the claimant, with the insurer's decision reviewed fresh rather than deferentially
Why it matters
Under ERISA, recovery in a benefits action generally centers on benefits owed under the policy, with interest and attorney fees potentially available. Under state law, an individually purchased policy may offer additional legal remedies, depending on the jurisdiction and the insurer’s conduct. Penalties, damages, and fee awards are not available in every case.
Determining whether a policy falls under ERISA is one of the first steps we take when reviewing disability insurance claims in New Orleans. The answer helps identify the deadlines, evidence, and legal options that apply to your claim.
Frequently Asked Questions
Do I need a lawyer for a disability insurance claim?
Most likely yes. It is always best to have a lawyer review your claim as soon as possible. A disability claim is a consequential process that will affect your income, your family, and your future for years to come, and you deserve a professional to guide you through it. Insurers have experienced claims staff and lawyers on their side. Decisions made early, such as what goes into your claim forms and appeal, can be impossible to undo later. Retaining Flinn Fezio at an earlier stage in the process will enable us to guide your claim best.
How do I know whether my policy is governed by ERISA?
If your employer provided or paid for the coverage, it is likely governed by ERISA. Coverage you bought on your own usually is not. There are exceptions, including government and church plans. We will review your policy and tell you which rules apply.
Do you handle Social Security Disability claims?
No. Our disability practice focuses on private disability insurance: group policies through employers and individual policies. We can refer you to a Social Security Disability attorney.
Speak With a
Personal Injury Lawyer
Early guidance can materially affect the outcome of your claim. We offer free initial consultations.